We’re Here to Help You
Every Step of the Way
Contact Us
SMG – SafeHarbor Management Group
Michigan
- Mon - Thu 8:00 am - 4:00 pm
Fri - Sat - Sun Closed
Florida
- 239-319-3062
- By Appointment only
Contact Us
Update Information
Resources
Medicare and You 2027
MEDICARE QUESTIONS
Clear answers to the questions we hear most about Medicare, including when to enroll, what each part covers, and how to choose the right plan for your needs.
MEDICARE AND YOU 2027
The official government handbook covering Medicare benefits, costs, enrollment periods, and plan options for 2027.
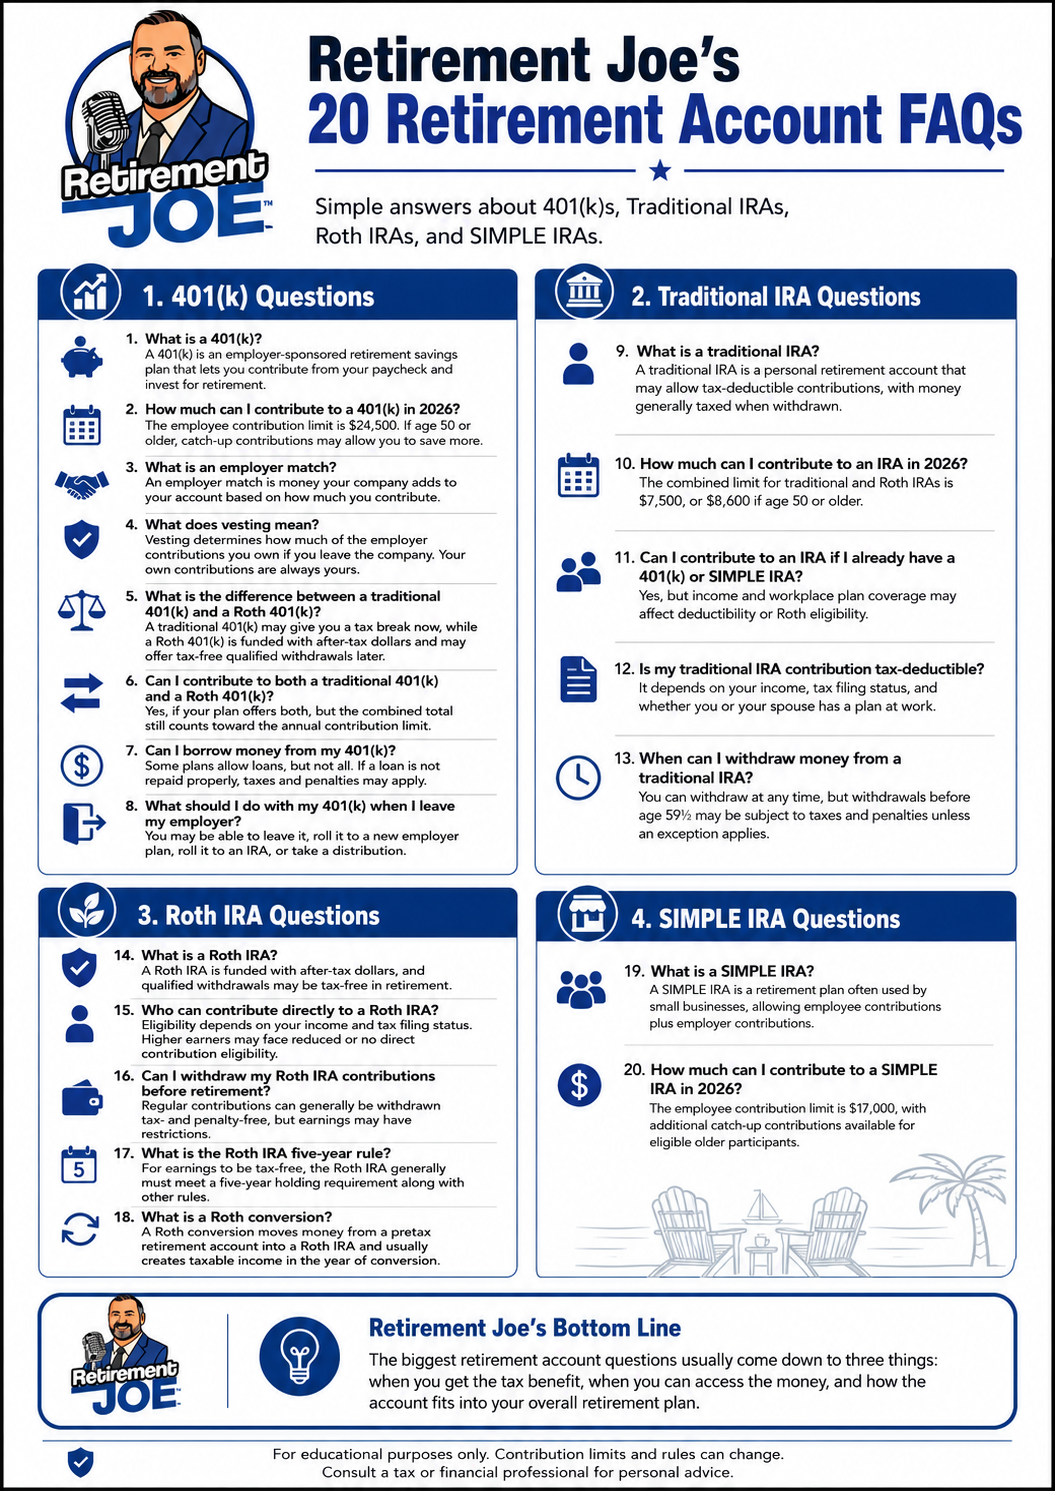
Retirement Account FAQs
RETIREMENT ACCOUNTS FAQs
Find answers to common questions about different types of retirement accounts, learn more about ínnous, retirements and & know much more.
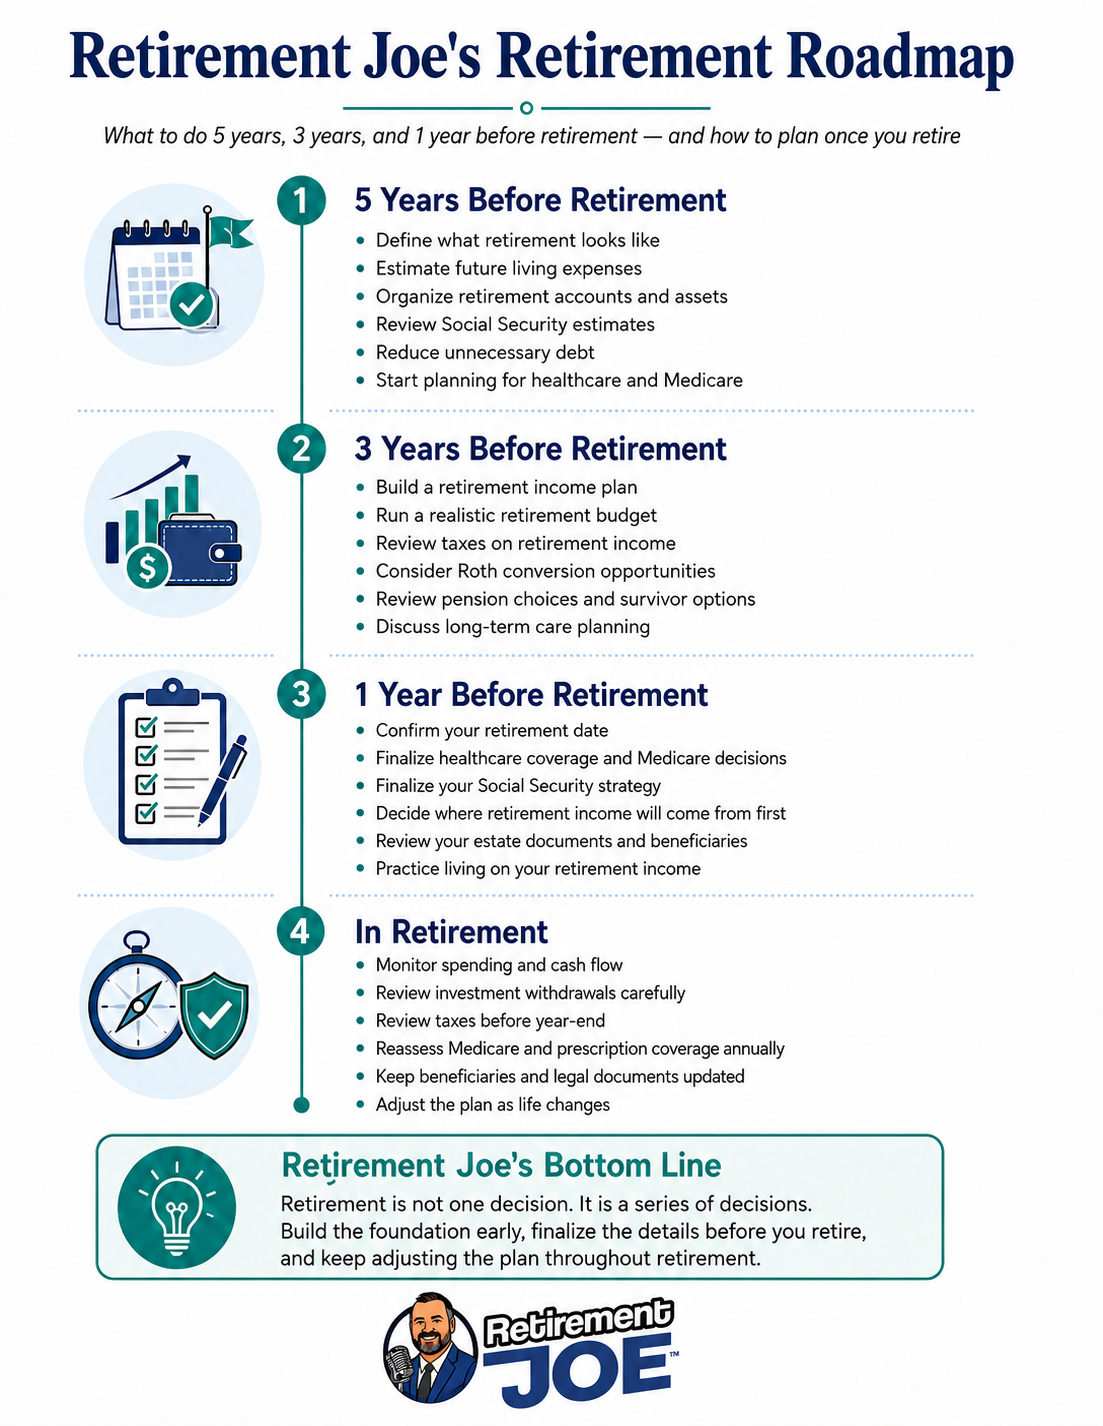
RETIREMENT ROADMAP
A comprehensive guide to planning your financial journey to retirement, to prannotize your nelocalonh, for end and metire more.
KEY RETIREMENT AGES AND DECISIONS
A quick reference to the ages and deadlines that matter most, including catch-up contributions, Medicare enrollment, Social Security, and required minimum distributions.
Medicare Questions
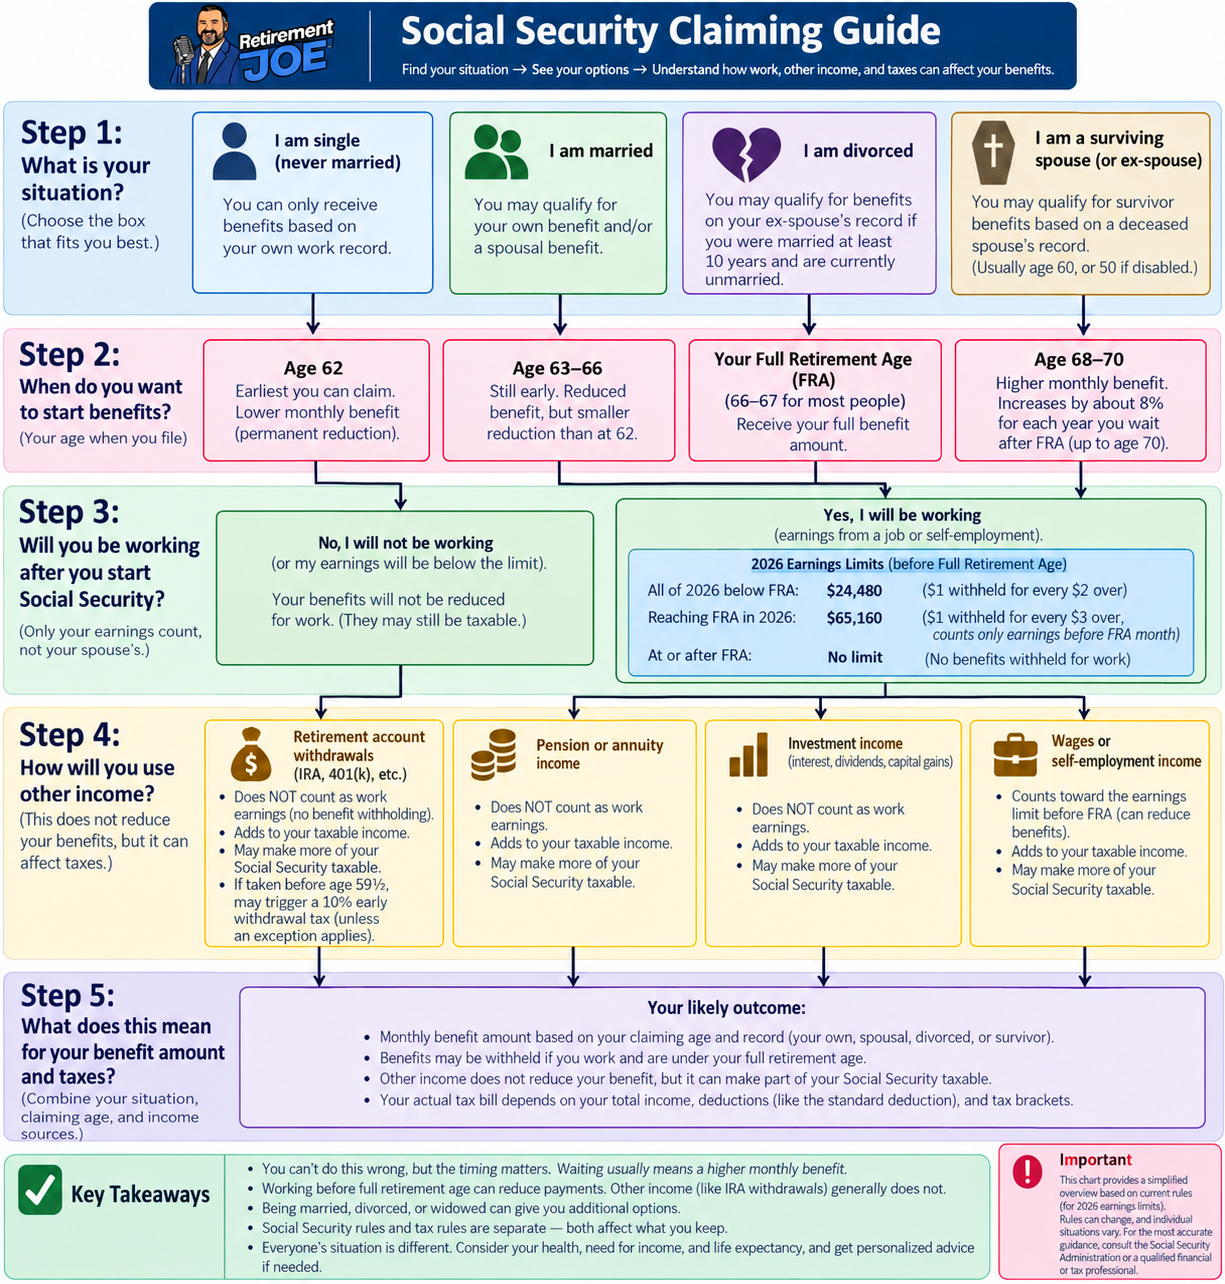
SOCIAL SECURITY CLAIMING GUIDE
Learn how your claiming age affects your monthly benefit, and explore strategies to help you decide when to start collecting Social Security.
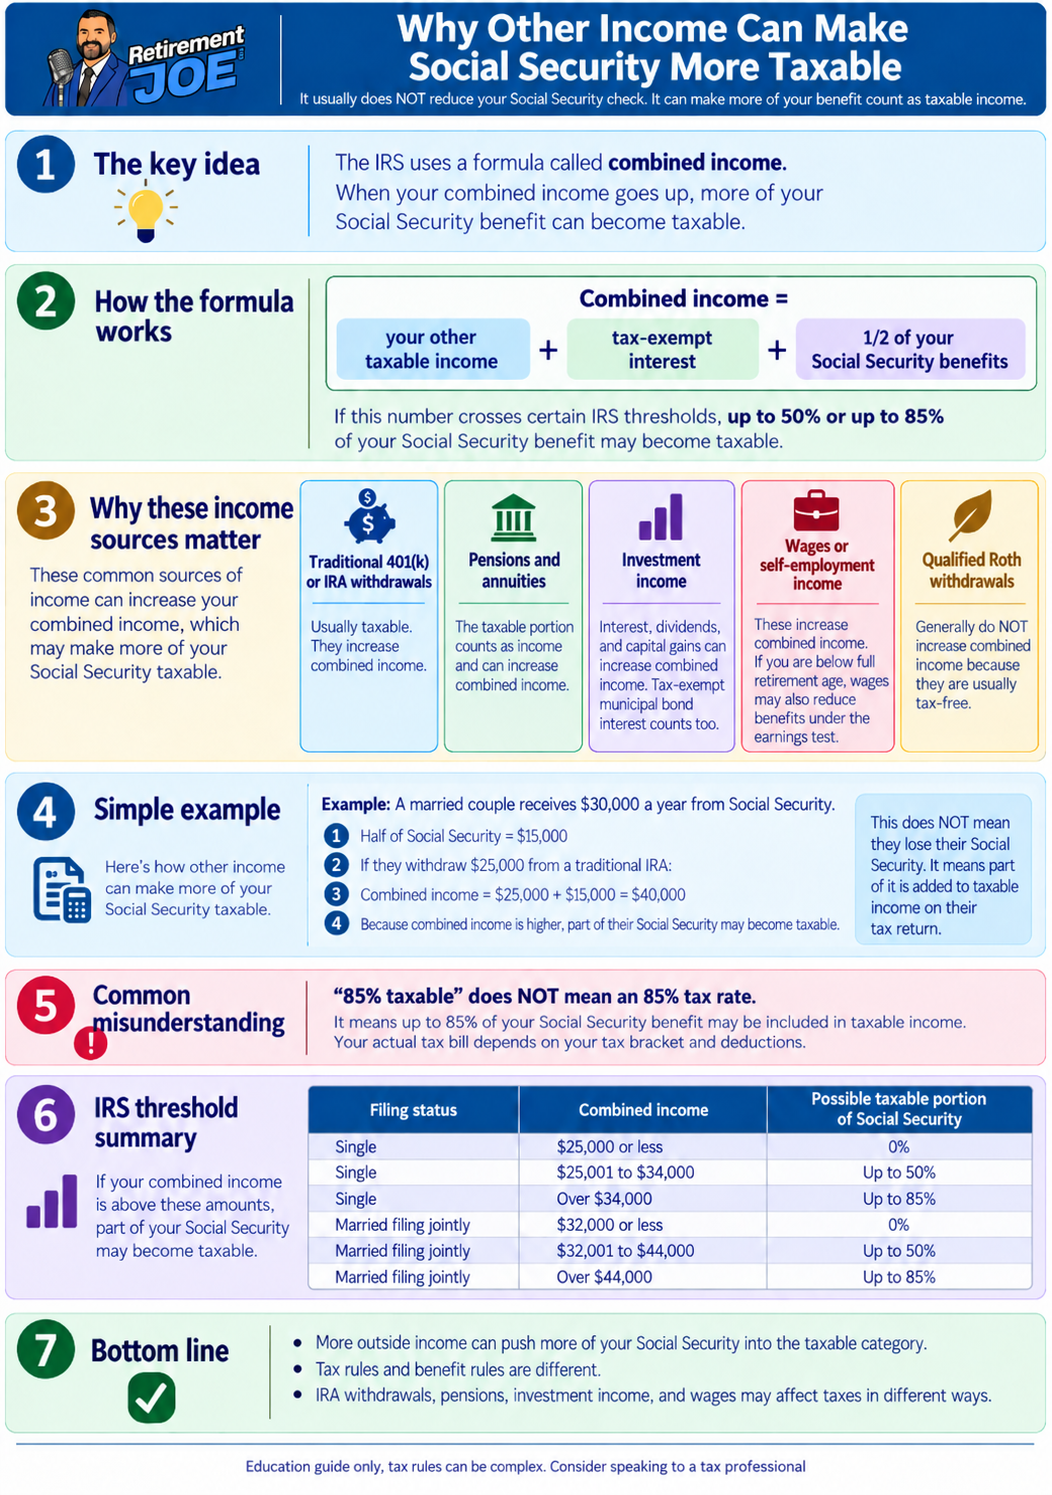
WHY OTHER INCOME MATTERS
Understand how pensions, retirement account withdrawals, and other income can affect the taxes on your Social Security benefits and your overall retirement income.
Retirement Joe's Retirement Roadmap
Plan ahead for the cost of extended care. Explore long-term care strategies, from traditional insurance to hybrid life and annuity solutions, designed to help protect your savings, your independence, and your family.
Social Security Guide
Why Other Income Matters
Knowledge is the first step toward a confident retirement. Our e-books break down important topics like retirement accounts, Medicare, and Social Security in plain English, so you can understand your options and make informed decisions at your own pace.
Turning 65 Medicare Checklist
Turning 65 comes with important Medicare decisions; this checklist helps you stay organized and confident every step of the way. Our free Turning 65 Medicare Checklist walks you through what to do, when to do it, and what to consider as you transition into Medicare.
Approach Medicare with clarity and confidence. You don’t have to navigate it alone. Our team is here for all your questions.
Medicare FAQ
If you sign up for a Medicare Supplement plan, you will also need to sign up for a prescription drug plan also known as Part D, even if you are not taking any medications. The government will penalize you 1% of the national base beneficiary premium by the number of uncovered months. For example, if you were uncovered for 12 months, you would owe 12% of the national base beneficiary premium. This penalty will be part of your Part D premium for ever.
Medicare is not free. Medicare Part A is free as long as you have worked 40 quarters. Medicare Part B has a standard monthly cost of $185 dollars. You could pay more for your Medicare Part B depending on your adjusted gross income, this is also known as Income related monthly adjustment amount (IRMAA).
Medicare Part A is for hospitalization, helps pay for anything that takes place while you are in the hospital. Medicare Part B is for outpatient doctor services. Medicare Part C is Advantage plan, and you have to stay in the advantage plans network of doctors. The Advantage plan generally will cost you more out of pocket when you use them. The typical out of pocket maximum is $5300 a year. The Medicare Part D is a stand-alone prescription drug plan. If you choose a Medicare Advantage plan the Part D is already included. If you choose a Medicare Supplement, you will need to purchase a Part D plan. Medicare Part was changed in 2025, the maximum out of pocket a consumer can pay is $2,000.00 for the year.
You may or may not be able to keep your doctors. If you sign up for a Medicare Advantage plan, you will be required to stay in a network. If your doctor is not in the network, then you would pay a higher cost to see them. If you sign up for a Medicare Supplement plan, your chances are higher that you will still be able to see your current doctor. Medicare Supplement plans do not have a network; you just have to see doctors that accept Medicare.
In general, you should sign up for Medicare Part A and Part B during your initial enrollment period, which starts three months before your 65th birthday, includes the month of your birthday and ends three months after that month. If you do not sign up during this period, you may have to pay a late enrollment penalty.
If you or a spouse is still working and have health coverage through an employer, you will not have to sign up for Medicare Part B.
get your complimentary analysis
Our complimentary portfolio analysis includes a Risk Assessment and a Portfolio Risk Analysis.
This will allow you to see how much risk you are taking in your current portfolio and compare it to other models.
Which of our services do you need help with today? Select the single option below that best fits your current goals, whether you want to see how your current portfolio’s risk stacks up against other models or need assistance with one of our other areas of expertise.
Get your Complimentary Navigating Medicare Guide
Our complimentary Navigating Medicare guide is designed to help you understand the basics. It will help navigate you through the different parts of Medicare, understand what is and isn’t covered, and help you understand the differences and similarities in Medicare Advantage and Medicare Supplement.